
Mortgage free before retirement - using the income you already earn
Your mortgage is the biggest lever in your finances. How it's structured quietly decides whether you walk into retirement free and clear, or still making payments at 65. Most homeowners have never seen what their current mortgage is really costing them.
Amanda Greville is a licensed Mortgage Agent Level 2 helping Ontario homeowners become mortgage-free before retirement through strategic mortgage planning.
No credit check. No pressure. Takes under 60 seconds.
The problem nobody shows you
Your mortgage is deciding when you get to retire
Most homeowners were handed the same story: pay your mortgage for 25 years, survive it, move on. Nobody asked whether the structure was costing them years and six figures they never agreed to lose.
- ✕ Your mortgage runs on default settings nobody ever optimized
- ✕ You earn well but feel like you should be further ahead
- ✕ Extra payments barely move the needle
- ✕ Budgeting harder changes nothing structural
- ✕ Chasing a lower rate at renewal saves a little, but the timeline didn't change
Part of why this matters more now: Canadians are buying their first homes later than they used to, and retiring later too. Statistics Canada puts the average retirement age at 65.3 in 2024, up from 64.3 just four years earlier, while Royal LePage's data shows a growing share of first-time buyers are now over 35. Later starts plus longer mortgages means more homeowners are heading toward retirement with years still left on the clock - exactly the gap the Mortgage Momentum Method is built to close.
The real lever is structure, not rate
What you pay over the life of a mortgage is driven mostly by how long you carry the balance, not the rate. The lowest rate can quietly cost you the most if the structure isn't working.
The Mortgage Momentum Method restructures how your income flows through your mortgage so the balance drops faster, without changing your lifestyle or having to earn more.
The Mortgage Momentum Method
See. Restructure. Accelerate.
A three-step system for turning a set-and-forget mortgage into a plan with a finish line you actually chose.
Step 1
See your number
I map your full picture - mortgage, debts, cash flow, equity, and the year you want to retire - and show you exactly what your current structure is costing you in years and dollars, with three paths compared side by side.
Step 2
Restructure your mortgage
I restructure how your income works against your mortgage so the balance drops faster and interest is reduced more often, without you changing your lifestyle. If the cashflow strategy isn't the right fit, I'll tell you and use a different tool.
Step 3
Accelerate to the finish line
I stay in your corner with check-ins and yearly reviews. Life changes, and so should your plan. Small adjustments compound, and the mortgage gets a finish line you can watch move closer.
Start with step one
Run the calculator and see how many years and how many dollars your current mortgage is costing you.
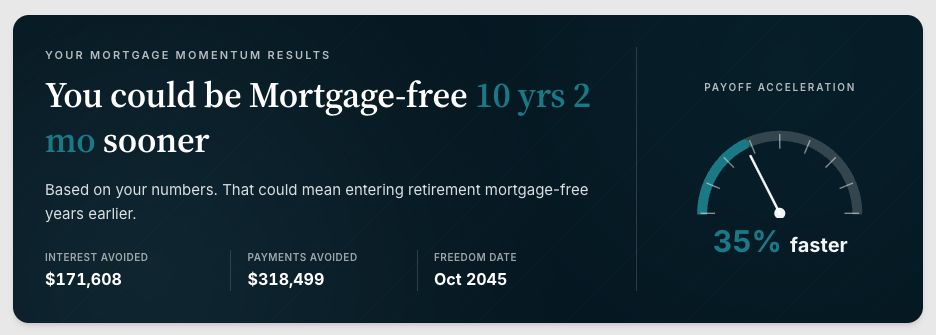
This is what your results look like. This sample homeowner found 10 years and $171k in interest they didn't know they had.
Illustrative example only. Your results depend on your actual mortgage, income, and cash flow.
No credit check. Takes under 60 seconds.
Is this right for you?
The Mortgage Momentum Method works best if you
- Own a home with at least 20% equity
- Earn a solid household income
- Have some money left over at the end of most months
- Feel like you should be further ahead financially
- Want a plan, not just another rate quote
- Are fairly disciplined with money and credit
Not sure how fast you could pay off your mortgage? Run the calculator - it takes under 60 seconds and there's no credit check.
Worth asking
Is restructuring always the right move?
No, and I'll tell you when it isn't.
The Mortgage Momentum Method works because it uses cash flow you already have left over each month. If there's no cushion there - if things are already tight by the time bills are paid - restructuring isn't going to manufacture money that isn't there, and I'm not going to pretend it will.
In that case, the right first move usually isn't your mortgage at all. It's looking at your full picture - debts, expenses, timing - and figuring out where the actual pressure is coming from. Sometimes that's a different conversation entirely, and I'll tell you that upfront instead of trying to fit you into a strategy that doesn't fit your life.
That's part of why the calculator and review are free: you find out which category you're in before anything moves forward.
A common question
Isn't it better to invest instead of restructuring my mortgage?
You'll see this question everywhere, and it's a fair one. If your mortgage rate is low and you could earn more investing that money elsewhere, sure, that math can work out in favour of investing.
But here's what that comparison usually misses: the Mortgage Momentum Method isn't about choosing between your mortgage and your investments. It's about freeing up cash flow that's currently locked into an inefficient structure - money that's just sitting there either way, doing nothing extra for you. Once it's freed up, what you do with it (pay down faster, invest, both) is still your call.
I'm not telling you to pick one over the other. I'm showing you the cash flow you didn't know you had to choose with.
What you walk away with
Your personalized Mortgage Momentum Plan
- ✓ Exactly how many years and how many dollars your current mortgage is costing you
- ✓ A side-by-side comparison: current mortgage vs. extra payments vs. the cashflow strategy
- ✓ A clear finish line - the year you could be mortgage-free
- ✓ More monthly cash flow, without earning more or cutting back
- ✓ A mortgage structure that works as hard as you do
- ✓ Ongoing reviews so the plan keeps moving as your life changes
- ✓ An honest answer about whether the strategy fits your situation
Getting started
How it works
You don't need to know anything about mortgage structure to get started. Here's what happens.
01
Run the calculator
Takes under 60 seconds. You'll see how many years and dollars your current mortgage is costing you, with no credit check and no obligation.
02
Book your free review
A 20-30 minute call where I turn your real numbers into a personalized Mortgage Momentum Plan - your finish line, your cash flow, your options.
03
I build your plan
I handle the restructuring, the paperwork, and the lender coordination. You don't need to figure anything out on your own.
04
We keep it moving
Regular check-ins and yearly reviews to make sure your plan stays on track as your income, expenses, and goals evolve.

Message from
Amanda Greville
Most homeowners I meet have done everything right. They earn well, they pay their bills, they've never missed a payment. And they still feel behind. The problem isn't their willpower or their income - it's their mortgage structure, and no one ever showed them.
I created the Mortgage Momentum Method because I believe no Ontario homeowner should carry a mortgage into retirement by accident. If my strategy fits your situation, I'll show you the path. If it doesn't, I'll tell you that too.
See your numberFrequently asked questions
What is the Mortgage Momentum Method?
It's a three-step system: See your number (understand what your current mortgage is really costing you), Restructure how your income works against your mortgage, and Accelerate to a finish line before retirement. It's not a product - it's a strategic approach to mortgage planning that uses the income you already earn.
How is this different from just chasing a lower rate?
Rate matters, but it's not the whole picture. What you pay over the life of your mortgage is driven mostly by how long you carry the balance. A slightly lower rate with the same 25-year structure can still cost you six figures in interest. The Mortgage Momentum Method focuses on reducing how long you carry the balance, which is usually the bigger lever.
Is this too good to be true?
I get this question a lot, and I respect it. The short answer: the calculator shows you your own real numbers with a disclaimer, not a promise. Nothing is guaranteed. But the math is real, and it's specific to your situation. If it doesn't fit, I'll tell you - walking away from the wrong fit is part of how I work.
Do I need to change my lifestyle or budget harder?
No. The method restructures how your income flows through your mortgage, not how much you earn or spend. If you have positive monthly cash flow now, that's what powers the strategy. You keep living your life the same way.
What if I don't have much extra cash flow each month?
Then I'll tell you that upfront. The Mortgage Momentum Method runs on cash flow that's already there at the end of the month. If that cushion doesn't exist right now, restructuring isn't going to create it - and pretending it would isn't something I'm interested in. In that case, we'd look at your full picture and figure out where the real pressure is coming from first. Sometimes the mortgage conversation comes after that one.
Isn't it better to invest instead of paying down my mortgage faster?
Sometimes, yes - and I'll say so when the math points there. But the Mortgage Momentum Method isn't really about choosing between the two. It's about finding cash flow that's currently locked in an inefficient structure and freeing it up. What you do with it once it's freed - invest, pay down faster, or both - is still your decision. I'm not here to tell you which is better for your life. I'm here to show you the cash flow you didn't know you had to choose with.
How soon will I see results?
You'll see clarity immediately - the calculator shows your numbers in under 60 seconds. Once the restructure is in place, the balance starts dropping faster right away. The full payoff plays out over years, but most homeowners see the balance dropping a lot more than their traditional mortgage would within the first month or two.
What does it cost to work with you?
Nothing for the vast majority of clients. I'm paid directly by the lender when I place your mortgage. The calculator is free, the mortgage review is free, and the ongoing reviews are free. In rare cases involving complex situations, a fee may apply - and I'll always tell you upfront.
Why should I start now instead of waiting?
Every month your mortgage sits on default settings, it costs interest and time that compounds. Starting sooner means more benefit builds up over the life of the mortgage. I won't pressure you - but your own numbers will show you why waiting is the expensive option.
Your mortgage has a finish line. Most people just never set one.
Run the calculator to see what your current mortgage is costing you, or book a free review and I'll walk you through your numbers personally.
No credit check. No pressure. You leave knowing your real options.